Transparency Sells Restaurants
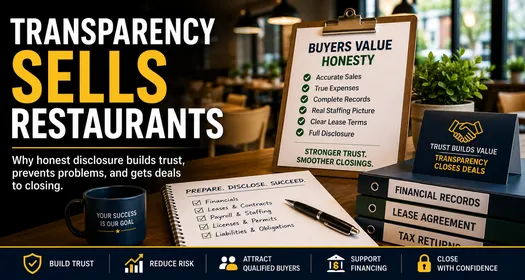
Transparency Sells Restaurants
Why Honest Disclosure Helps Deals Reach Closing
Most restaurant owners do not intentionally mislead buyers.
Problems often begin with small omissions, optimistic assumptions, or an effort to present the business in the best possible light. But once due diligence begins, even a minor inconsistency can raise larger questions.
In a restaurant sale, trust matters. When early claims do not match the records, buyers become cautious, lenders slow down, and advisors begin looking for additional problems.
Due Diligence Finds the Gaps
Buyers and lenders will review nearly every important part of the business, including:
- Sales
- Expenses
- Payroll
- Staffing
- Lease terms
- Equipment
- Licenses
- Contracts
- Liabilities
- Operating practices
A buyer may love the restaurant, but that does not eliminate the need to verify the information provided.
Unreported Sales Usually Do Not Count
Sellers sometimes say actual revenue is higher than what appears on tax returns, POS reports, or bank statements.
That creates a major problem.
If sales cannot be documented, buyers may not include them when calculating value. Lenders are also unlikely to use unsupported revenue when determining whether the business can repay a loan.
Unreported sales may make the restaurant seem more profitable in conversation, but they rarely help when the transaction must be supported by records.
Understated Expenses Reduce Confidence
Minimizing expenses can make earnings look stronger than they really are.
Problems arise when buyers later discover higher costs for:
- Payroll
- Food and beverage
- Repairs
- Insurance
- Utilities
- Delivery platforms
- Rent
- Equipment leases
- Owner replacement labor
When actual expenses differ significantly from the original presentation, the buyer may reduce the offer, request new terms, or walk away.
Staffing Problems Matter
Labor is one of the largest risks in a restaurant acquisition.
Buyers need to understand:
- Which employees are likely to stay
- Whether key managers are essential
- Whether the owner fills an unpaid role
- Whether staffing levels are adequate
- Whether payroll is fully reported
- Whether there are wage or compliance concerns
If the restaurant depends heavily on the seller or a key employee who plans to leave, that should be disclosed early.
A buyer can often plan for a known staffing challenge. A surprise discovered late in the process is much harder to overcome.
Lease Surprises Can Kill the Deal
The lease is often one of the most important assets in a restaurant sale.
Unexpected problems may include:
- A short remaining term
- No renewal options
- Rent increases
- Personal guarantees
- Assignment restrictions
- Landlord approval requirements
- Unpaid rent
- Use restrictions
- Required renovations
A strong restaurant can become difficult to sell if the buyer cannot secure the location.
Sellers should review the lease carefully before listing and disclose important limitations before the buyer invests substantial time and money.
Small Omissions Create Bigger Questions
The issue is not always the undisclosed fact itself.
The greater concern is what the omission suggests.
When a buyer discovers one hidden expense, missing contract, or inaccurate statement, the natural question becomes:
What else has not been disclosed?
That loss of confidence can lead to broader document requests, slower negotiations, price reductions, or termination of the deal.
Transparency Does Not Mean the Business Must Be Perfect
Most restaurants have challenges.
A business may have aging equipment, a short lease, staffing difficulties, inconsistent sales, or deferred maintenance. These issues do not automatically prevent a sale.
The strongest transactions are often those in which the seller:
- Identifies problems early
- Provides accurate records
- Explains unusual expenses
- Documents legitimate add-backs
- Discloses known liabilities
- Sets realistic expectations
- Offers practical solutions
Buyers are more likely to accept a known issue than an unexpected one.
Prepare Before Going to Market
Before listing a restaurant, sellers should review:
- Tax returns
- Profit-and-loss statements
- POS reports
- Bank deposits
- Payroll records
- Lease documents
- Equipment obligations
- Gift-card liabilities
- Rewards-program liabilities
- Vendor contracts
- Licenses and permits
- Pending legal or compliance issues
Any inconsistency should be explained and documented before buyers begin asking questions.
This preparation helps the seller control the story rather than react to problems during due diligence.
The Bottom Line
Little white lies rarely stay little during a restaurant sale.
Unsupported sales, understated expenses, staffing surprises, and lease problems can damage trust and weaken a deal. Accurate disclosure gives buyers confidence, helps lenders evaluate the transaction, and reduces the chance of last-minute renegotiation.
Transparency does not reduce value. In many cases, it protects it.
Ready to Buy or Sell a Restaurant?
SellYourRestaurant.com was built specifically for restaurant owners, buyers, brokers, and hospitality investors. Our platform helps buyers discover restaurant opportunities while giving sellers the tools to market their business confidentially and professionally.
Reach qualified buyers. Protect your business. Close the deal.
This article is for general informational purposes only and should not be considered legal, financial, tax, or professional advice.