Live Oak Pulled Back and Huntington Nearly Doubled: Who Made the Most $2 Million-Plus SBA Acquisition Loans, as Tallied Oct. 23, 2026
SBA LENDERS | NATIONAL
A newsletter's count of 808 large SBA loans to business buyers shows the busiest lenders trading places, and why a cheap term sheet means little if the bank can't close.
By SYR News | Oct. 26, 2026
The This Week in ETA newsletter, which covers buying and running small businesses, pulled every SBA acquisition loan of $2 million or more, without real estate, approved over the past 12 months in all industries. It published the results on Oct. 23: 808 loans totaling $2.7 billion.
Both figures rose from the year before, by 14% in number of loans and 12% in dollars, the newsletter said, even though the October government shutdown wiped out about a month of approvals.
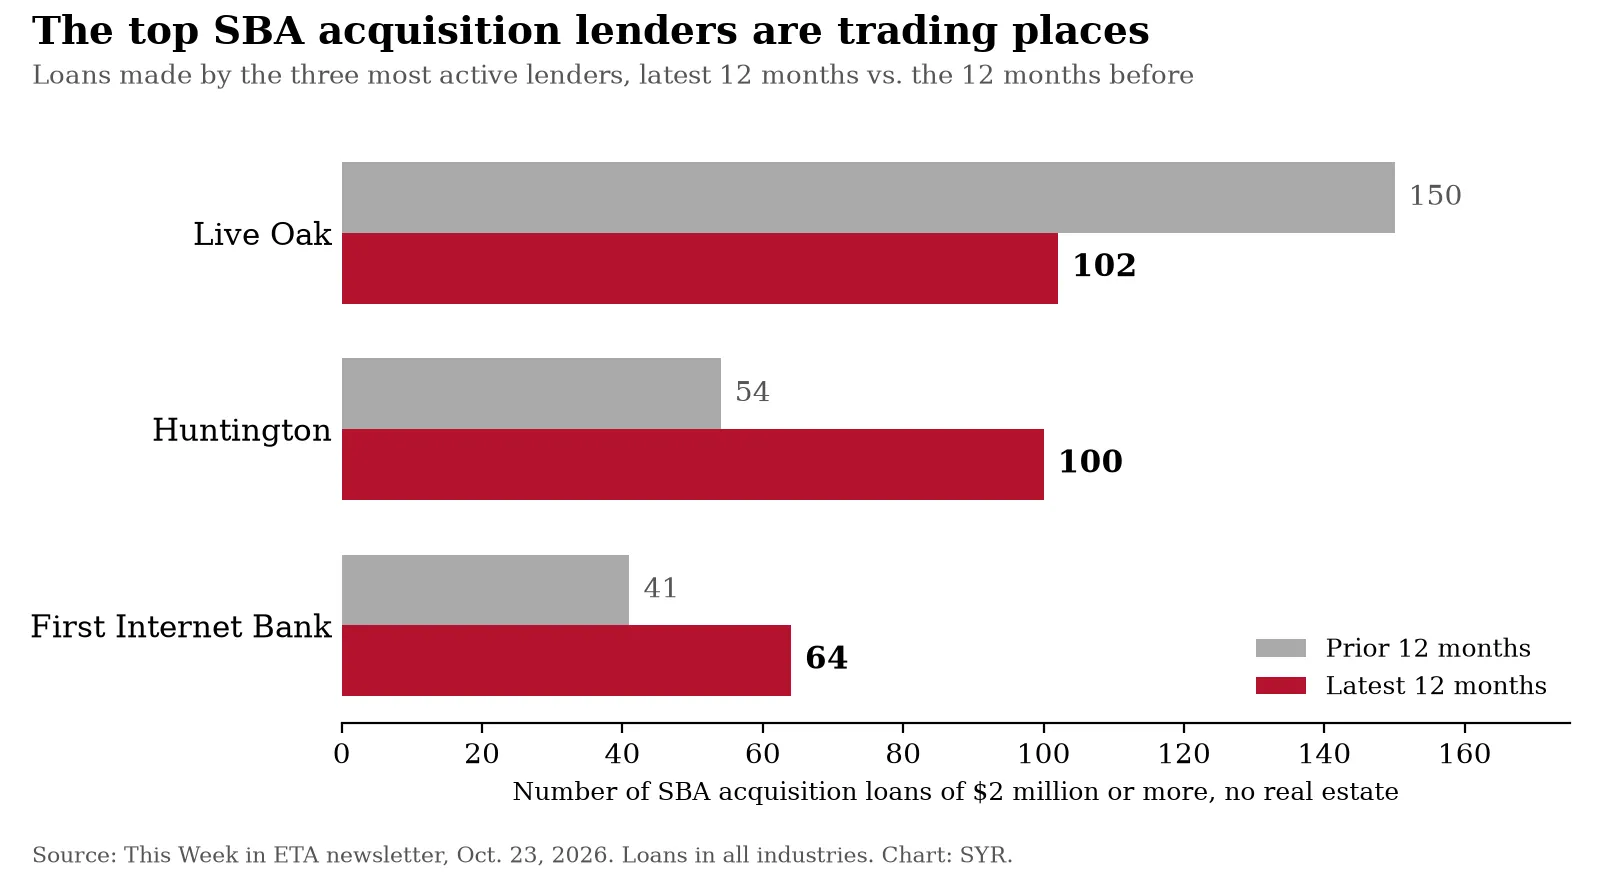
Loans of $2 million or more for business acquisitions without real estate made by the three most active SBA lenders, latest 12 months vs. the prior 12. Source: This Week in ETA. Chart: SYR.
The lender scoreboard
- Top 10 lenders: 49% of the 808 loans
- Live Oak: 102 loans, down from 150; its share fell from 21% to 13%
- Huntington: 100 loans, up from 54, nearly tied for the top spot
- First Internet Bank: third, with 64 loans, up from 41
- Pathward and Byline Bank: fourth and fifth (loan counts not reported)
- The eight largest U.S. banks: 20 of these loans combined
“A low rate is worth little if the loan never reaches the closing table”
Why the name on the term sheet matters
The newsletter's authors wrote that working with a bank that makes many SBA acquisition loans gives a buyer more confidence the deal will actually close. Smaller banks sometimes offer attractive rates and terms, they said, then struggle when a credit committee that rarely sees acquisition loans reviews the file. In their view, a cheap term sheet that dies in committee costs a buyer more than the rate savings would ever return.
Put simply, a low rate is worth little if the loan never reaches the closing table. The count covers loans of $2 million and up, above the size of most independent restaurant deals, and it includes every industry, not just restaurants. The point about choosing an experienced lender applies at any size.
Three closings that slipped, and why
The same issue carried a piece by Chat Joglekar of Baton, a business-for-sale platform, on three acquisitions that closed in summer 2026 after delays caused by a third party. None was a restaurant, and none used an SBA loan.
- The landlord: after the letter of intent was signed, a pet-boarding business's landlord refused to pay for an estimated $125,000 to $150,000 in air-conditioning and water upgrades; the closing date slipped three times and the seller gave back $60,000
- The lender: a therapy practice priced at $778,000 drew offers near the asking price, but lenders capped the loan at about $450,000, and it sold for $525,000
- The franchisor: a first-time buyer's $200,000 franchise purchase stalled for seven weeks while the franchisor renewed its California franchise registration
What restaurant buyers and sellers can take from it
- Buyers: ask each lender how many acquisition loans it closed in the past year, and how many were for restaurants
- Buyers: get at least one term sheet from a high-volume SBA acquisition lender, even if a local bank quotes a lower rate
- Sellers: set a price a lender will finance; the therapy practice sold for about two-thirds of its asking price
- Sellers: settle repair and improvement duties with the landlord before a letter of intent is signed
- Franchise owners: confirm with the franchisor which approvals and state filings a transfer needs, and how long they take
Key Takeaways
- This Week in ETA counted 808 SBA acquisition loans of $2 million or more without real estate over the past 12 months, totaling $2.7 billion.
- Live Oak's count fell to 102 from 150 as Huntington's nearly doubled to 100; First Internet Bank was third with 64.
- The eight largest U.S. banks made only 20 of these loans combined.
- A lender that regularly closes acquisition loans can matter more to a buyer than a lower rate.
More from SYR News
- SBA 7(a) Approvals Fell 13% in FY2026, but Some Lenders Nearly Doubled. Why Restaurant Buyers Should Shop Around
- The Busiest SBA Lender Charged 10.65% in Q2 2026, While U.S. Bank Charged 9.04%. Restaurant Buyers Should Get Three Quotes
- Full-Service Restaurants Were the No. 1 Business Bought With SBA 7(a) Loans in the Year to June 30, 2026
- A Lender's Read on the Oct. 1, 2026 SBA Rules: Restaurant Deals Now Have to Work on Last Year's Numbers
- New Checklists, More Documents: How SBA Lenders Retooled for the Oct. 1, 2026 Rules
- SBA Loan Approvals Fell by Double Digits in FY2026. Since Oct. 1, the Bar Is Even Higher
Sources
This Week in ETA, "Who's Actually Lending to Business Buyers Right Now" (Oct. 23, 2026): https://thisweekineta.beehiiv.com/p/who-s-actually-lending-to-business-buyers-right-now