SBA Loan Approvals Fell by Double Digits in FY2026. Since Oct. 1, the Bar Is Even Higher
SBA LENDING
SBA's flagship 7(a) program closed fiscal 2026 with fewer loans and fewer dollars, and the acquisition rules that took effect Oct. 1 tighten underwriting again. Restaurant buyers should expect slower, choosier lenders this fall.
By SYR Staff | Oct 15, 2026
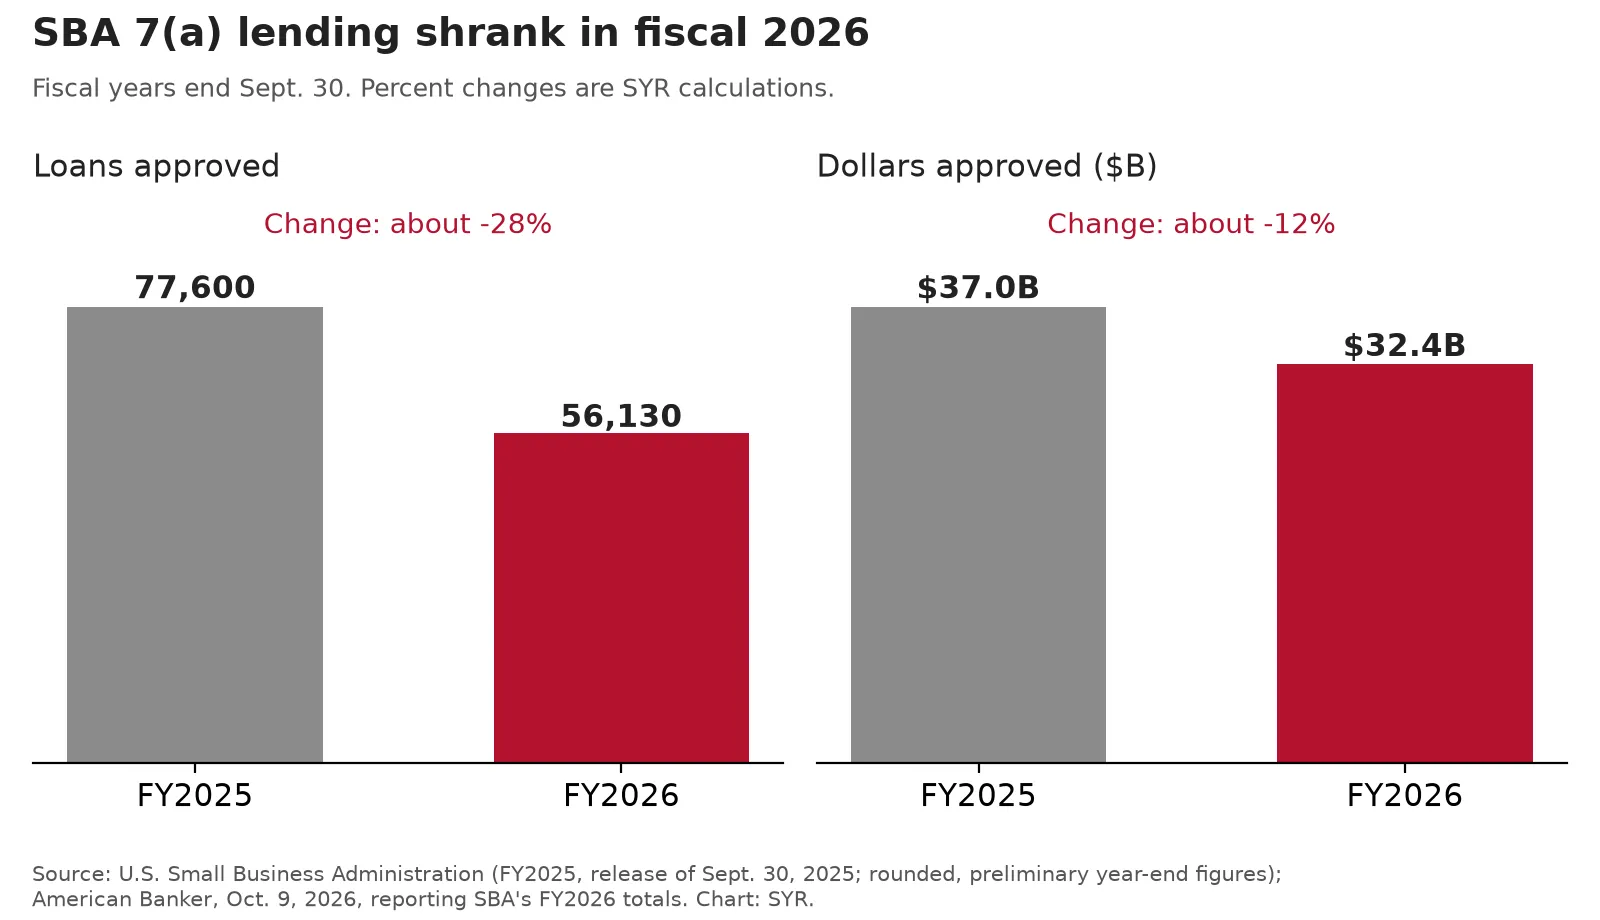
SBA 7(a) approvals, FY2025 vs. FY2026. Source: U.S. Small Business Administration (Sept. 30, 2025); American Banker (Oct. 9, 2026). Chart: SYR.
Fewer loans, fewer dollars and stricter rules: that is how SBA's flagship lending program heads into fiscal 2027. American Banker reported Oct. 9 that SBA approved 56,130 loans under its 7(a) program in fiscal 2026, which ended Sept. 30, for a combined $32.4 billion. Both measures fell by double-digit percentages from the year before.
SBA's own year-end announcement for fiscal 2025 put that year at roughly 77,600 7(a) loans and $37 billion. Measured against those rounded figures, the loan count dropped about 28% and dollar volume about 12%. Because dollars fell less than deal count, the average loan got bigger, a hint that smaller transactions absorbed more of the decline.
By the numbers
- FY2026 7(a) approvals: 56,130 loans, $32.4 billion (American Banker, citing SBA)
- FY2025 7(a) approvals: about 77,600 loans, $37 billion (SBA, Sept. 30, 2025)
- Implied average 7(a) loan: about $477,000 in FY2025 vs. about $577,000 in FY2026 (SYR calculation)
- 504 program: dollar volume down 9% to $7.1 billion
- Live Oak, the No. 1 7(a) lender: volume down 9% to about $2.6 billion
“SBA money hasn't disappeared. It now flows to deals that can document their earnings.”
Two rule changes, one direction
The first round of tightening came in June 2025, when SBA reinstated a 10% equity injection for startups and changes of ownership and narrowed its rules on personal guarantees and small-dollar loans. The second arrived Oct. 1, 2026, when SOP 50 10 8.1 began governing applications SBA receives from that date on. Its biggest changes land on business acquisitions, the category most restaurant buyers fall into.
- First-time buyers (Initial Acquisitions) must show at least 1.25x debt service coverage on the last fiscal year or a two-year average. Lenders must review projections but can't use them to reach that number.
- Standby seller notes and other limited equity sources can supply no more than half of the required 10% injection.
- A quality-of-earnings report is required once the business purchase price reaches $3 million.
- Total acquisition debt, including any seller note that receives payments, can't exceed the business valuation.
Rules weren't the only drag. American Banker also pointed to SBA's bar on loans to businesses owned by lawful permanent residents, and to a Lumos Group study finding that borrowers hurried to close ahead of the fall 2025 government shutdown, pulling some fiscal 2026 loans into fiscal 2025.
Views split on whether the tightening was needed. “The credit box shrunk,” Eric Rabinovich, founder of SBA Loan Lab, told the publication. Kapitus COO Ben Johnston argued the agency had to course-correct to restore the program's financial health.
What it means for a local restaurant deal
SBA money hasn't disappeared. It now flows to deals that can document their earnings. Buyers should expect lenders to ask for tax returns, bank statements and sales records up front, to strip out add-backs without paper behind them, and to take longer to issue a commitment. Sellers who price off a best-case earnings figure will find that SBA-financed buyers can't follow them there.
Key Takeaways
- SBA approved 56,130 7(a) loans worth $32.4 billion in FY2026, both down by double digits.
- Since Oct. 1, acquisition loans need 1.25x coverage on historical earnings, tighter equity sourcing and total debt capped at the valuation.
- Buyers: line up documented financials and a lender conversation before you sign an LOI.
- Sellers: price to earnings a lender can verify.
Sources
American Banker, "SBA starts new fiscal year with even tighter credit box" (John Reosti, Oct. 9, 2026; updated Oct. 13): https://www.americanbanker.com/news/sba-starts-new-fiscal-year-with-even-tighter-credit-box
U.S. Small Business Administration, "Trump SBA Delivers Record Capital to Small Businesses in FY25" (Sept. 30, 2025): https://www.sba.gov/article/2025/09/30/trump-sba-delivers-record-capital-small-businesses-fy25
U.S. Small Business Administration, Information Notice 5000-882227, Issuance of Technical Updates to SOP 50 10 8.1 (Sept. 25, 2026): https://www.sba.gov/document/information-notice-5000-882227-issuance-technical-updates-sop-50-10-81
U.S. Small Business Administration, SOP 50 10 8.1, Lender and Development Company Loan Programs, with Technical Policy Updates (effective Oct. 1, 2026): https://www.sba.gov/document/sop-50-10-lender-development-company-loan-programs
Images and Graphics
Chart: original SYR chart built from figures in SBA's Sept. 30, 2025 release (FY2025) and American Banker's Oct. 9, 2026 report (FY2026).