Only 47% of Restaurant Listings Pass the SBA's 1.25x Test. Pizzerias, Cafes and Bars Mostly Don't
DEAL MATH
A test of more than 26,100 business-for-sale listings finds the median restaurant clears SBA's Oct. 1 coverage bar with modest room to spare, while many smaller food concepts are priced beyond what a lender can carry.
By SYR Staff | Oct 15, 2026
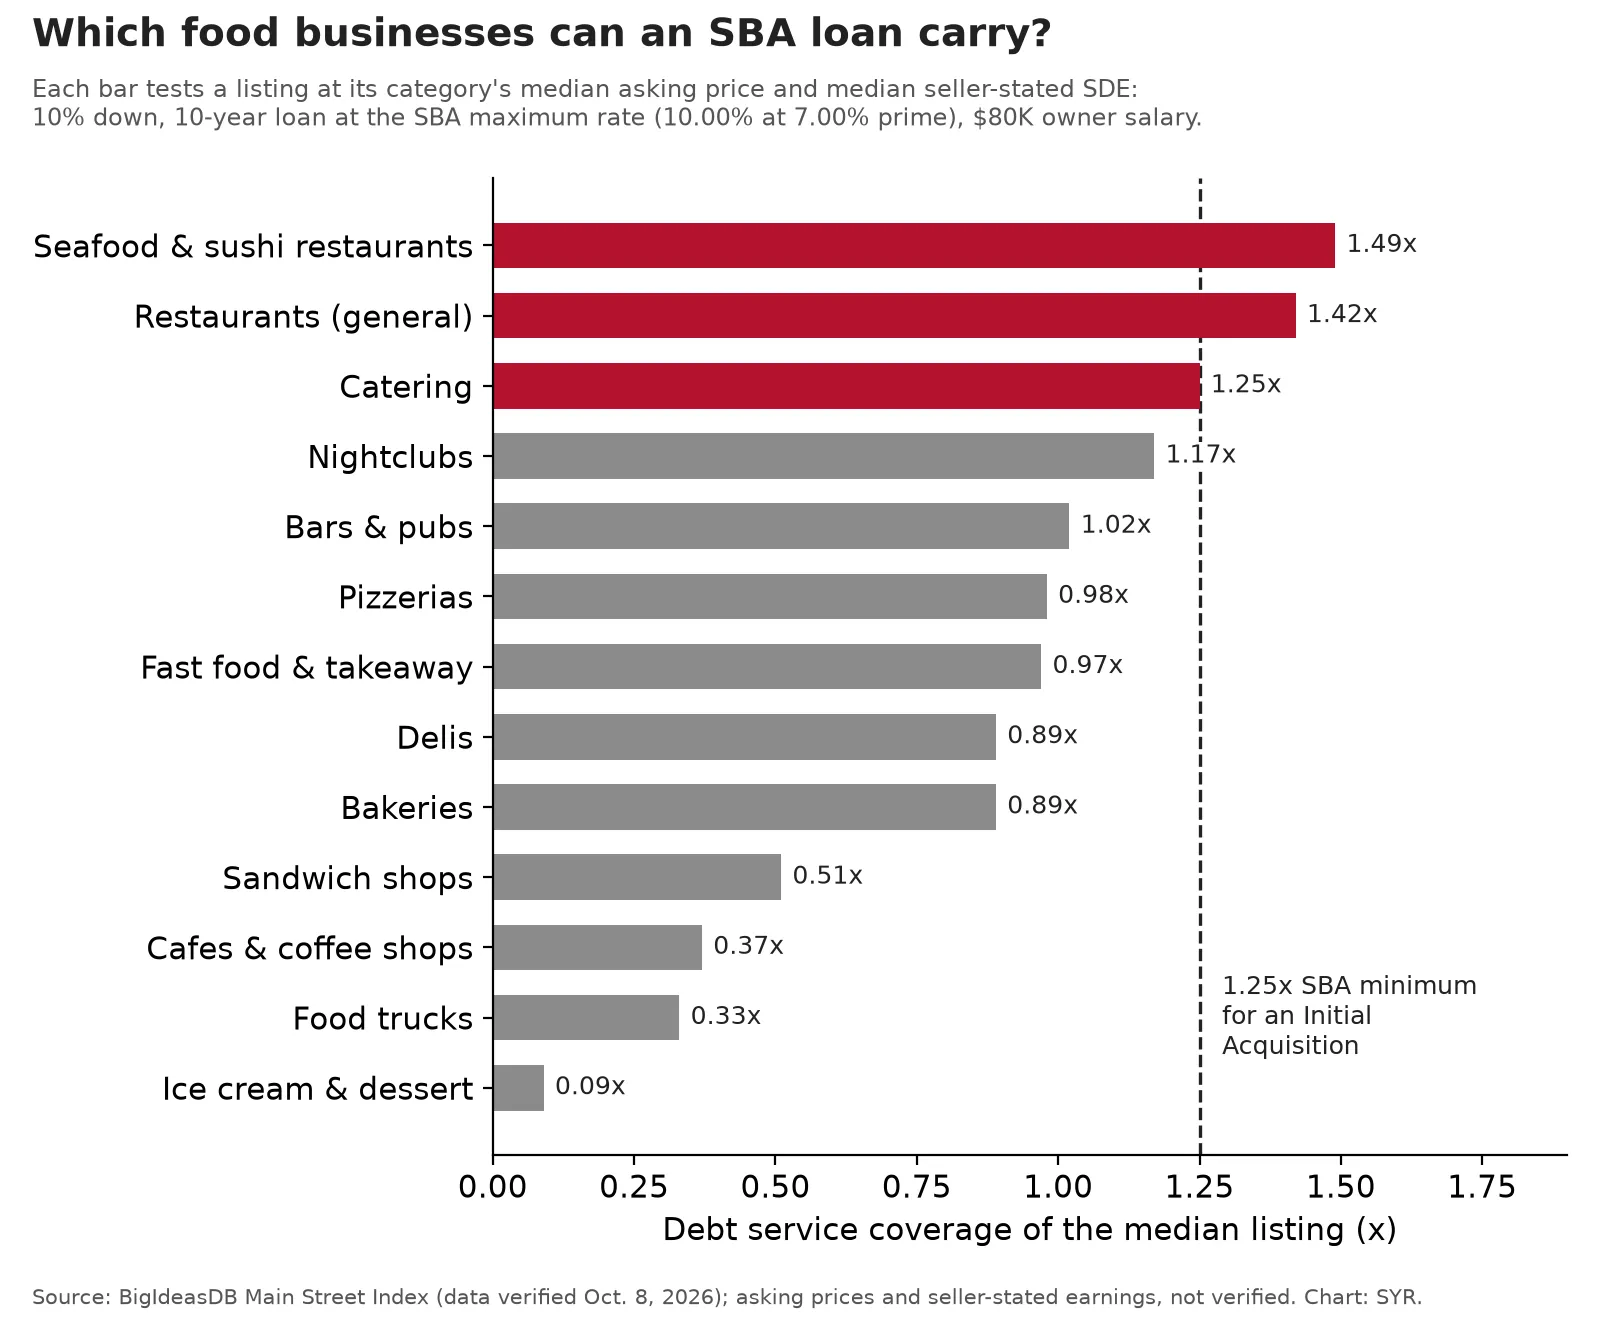
Debt service coverage of the median listing, by food category, at the SBA maximum rate with an $80K owner salary. Source: BigIdeasDB Main Street Index (data verified Oct. 8, 2026). Chart: SYR.
Will an SBA loan actually carry the restaurant you want to buy? BigIdeasDB, which maintains a database of businesses for sale, ran more than 26,100 priced U.S. listings through the coverage rule that took effect Oct. 1. The short version: the typical restaurant passes, though not by much, and many of the food businesses first-time buyers look at don't pass at all.
The assumptions behind the test
- Loan: SBA 7(a), up to $5 million, 10-year term for the business portion, at least 10% down
- Rate: SBA's maximum of 10.00%, with prime at 7.00%
- Owner salary taken out before coverage is measured: $80,000
- Pass mark: 1.25x debt service coverage on historical earnings
- Inputs: asking prices and seller-stated earnings, not closed sales or audited books
“Shop for earnings, not for the category on the sign.”
The results
- Across all industries, 40.1% of priced listings pass.
- The median restaurant listing (2,000-plus listings) asks $370,000 on $165,000 of seller's discretionary earnings and covers its debt 1.42 times.
- Yet only 47.1% of individual restaurant listings pass.
- At their category medians, pizzerias (0.98x), fast food and takeaway (0.97x), bars and pubs (1.02x) and cafes and coffee shops (0.37x) all fall short.
- At the typical asking multiple of 2.67x, a business needs roughly $174,000 of earnings before an SBA loan works.
Earnings, more than price, set the limit. Once a lender carves out a living wage for the owner, a small coffee shop has little left to service debt. By BigIdeasDB's math, the median cafe, with $97,000 of stated earnings, could support an SBA-financed price of only about $73,000, against a median ask of $243,000.
Failing at the median isn't failing everywhere
A category that misses at the median isn't off-limits. It means the typical listing is priced for a cash buyer or a seller-financed deal. BigIdeasDB estimates that a pizzeria with $200,000 of stated earnings could carry an SBA-financed price of about $595,000. Shop for earnings, not for the category on the sign.
For sellers and brokers
Run the test before the listing goes live. Start with documented earnings, subtract a realistic owner salary, divide by 1.25 and compare the result with the annual payment on the loan a buyer would need. If the price works only for an all-cash buyer, either price for that smaller pool or be ready to carry a standby note.
Key Takeaways
- The median restaurant listing clears SBA's 1.25x test at 1.42x, but fewer than half of restaurant listings pass.
- Pizzerias, fast food, bars and cafes fall short at their category medians.
- Owner earnings drive the result. About $174,000 is the practical floor at typical asking multiples.
- Run the coverage math before listing, or plan for cash buyers and seller financing.
Sources
BigIdeasDB, "SBA loan to buy a business: the 2026 rules, today's rate, and which deals clear 1.25x" (Om Patel, updated Oct. 8, 2026): https://bigideasdb.com/sba-loan-to-buy-a-business
U.S. Small Business Administration, SOP 50 10 8.1, Lender and Development Company Loan Programs, with Technical Policy Updates (effective Oct. 1, 2026): https://www.sba.gov/document/sop-50-10-lender-development-company-loan-programs
Images and Graphics
Chart: original SYR chart built from BigIdeasDB Main Street Index figures (data verified Oct. 8, 2026).