Since Oct. 1, SBA's Sept. 25 Rewrite, Not the August Draft, Sets the Rules for Buying a Restaurant
SBA FINANCING
Summaries written to the August text are still making the rounds. Here is what the governing version of SOP 50 10 8.1 requires on equity, coverage, debt and the seller's role after closing.
By SYR News | Oct. 16, 2026
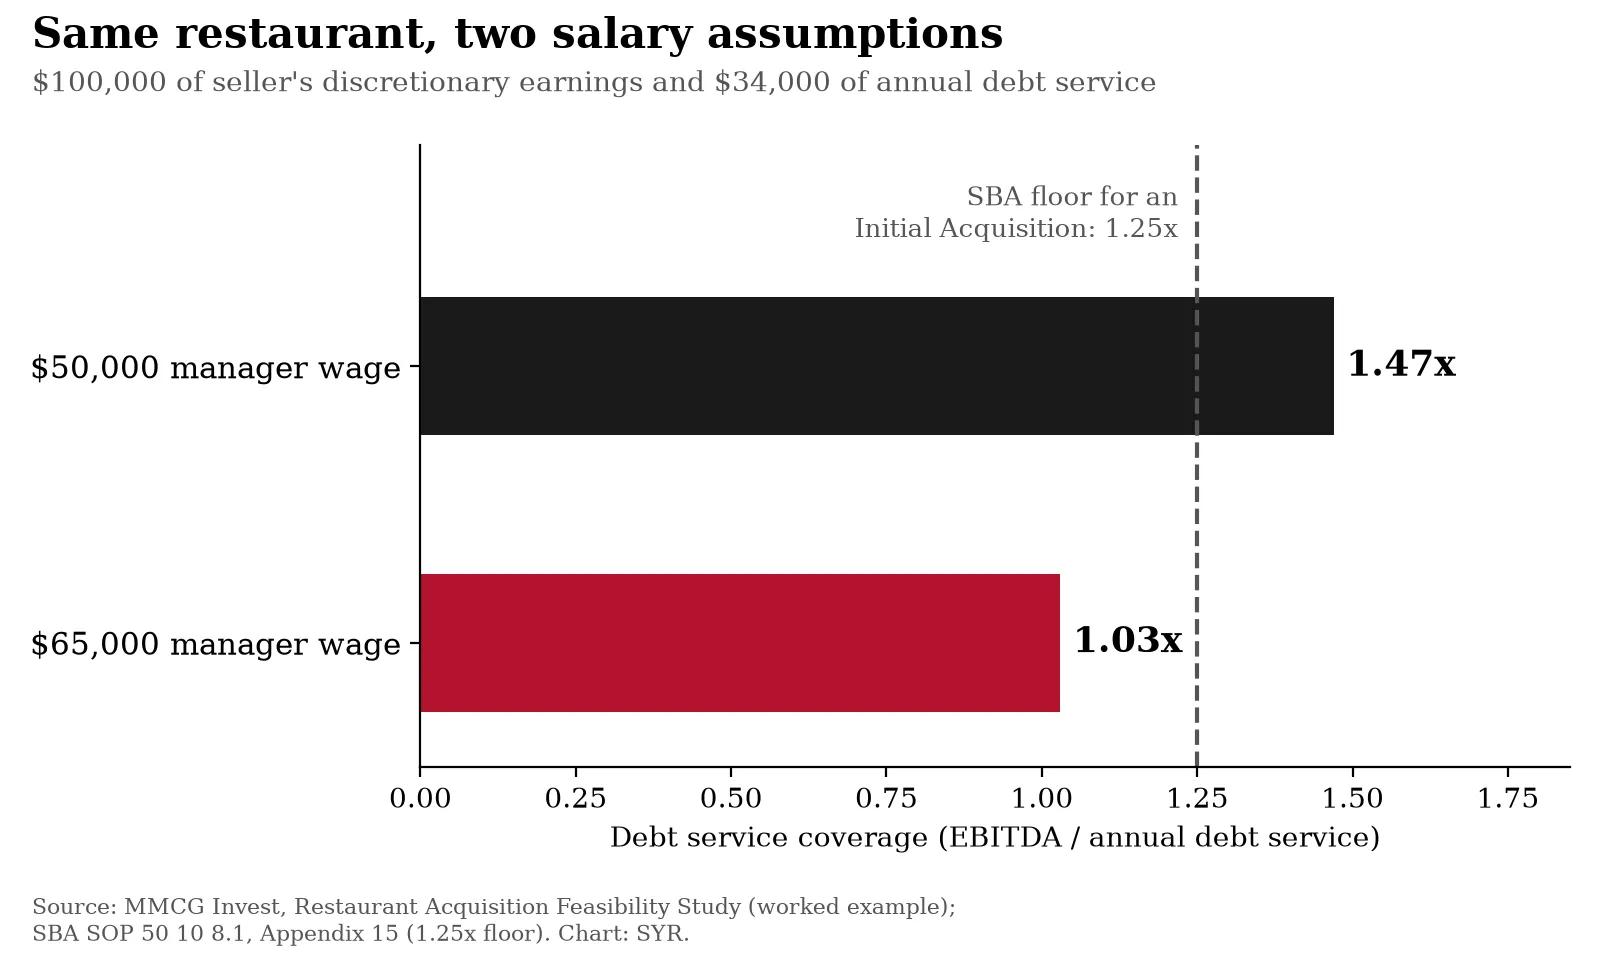
Coverage for one restaurant under two replacement-manager salaries. Source: MMCG Invest (worked example); SBA SOP 50 10 8.1, Appendix 15. Chart: SYR.
SBA published SOP 50 10 8.1 on Aug. 14, 2026, then replaced it on Sept. 25 with a version carrying Technical Policy Updates, days before the rules took effect. Restaurant feasibility firm MMCG Invest makes the point plainly on its acquisition-study page: the September text is the one that governs, and some widely shared summaries still describe the August draft.
SBA's Sept. 25 notice ties the new SOP to applications SBA receives on or after Oct. 1, 2026. Applications submitted through Sept. 30 stay under the previous SOP 50 10 8.
The rules for a first-time buyer
- Category: a buyer who was not already an owner or employee is an Initial Acquisition, and any deal that fails the tests for the other categories lands here by default
- Equity: at least 10% of total project cost, which can't be reduced or eliminated
- Limited sources: standby seller debt, other standby debt and qualifying minority investors can together supply no more than half of that 10%
- Coverage: at least 1.25x, measured on the last fiscal year or the average of the last two; lenders may review projections but can't use them to reach the floor
- Debt cap: total acquisition debt, including any seller note that isn't on full standby, can't exceed the business valuation
- Valuation: prepared for the lender by a qualified independent source, though the lender may do its own when the business purchase price is $350,000 or less and buyer and seller aren't closely related
- Quality of earnings: required when the business purchase price is $3 million or more
“The salary a lender assumes for the new manager can decide whether a small restaurant deal qualifies.”
If you already run a restaurant
An operator with two full fiscal years under current ownership who buys another business in the same industry group can qualify as a Business Expansion. That category carries a lower 1.15x coverage floor, and the lender may reduce the equity requirement if the buyer shows enough liquidity.
The seller's role after closing
- In an Initial Acquisition or Business Expansion, the seller can stay on only as a consultant, for no more than 24 months in total
- Seller earnouts are prohibited; performance-based rebates to the buyer are allowed
- A seller note becomes eligible for refinancing only after it has been in place and current, and not on standby, for at least 36 months after the sale
Where small deals are decided
MMCG argues that for many restaurant purchases the 1.25x floor isn't the binding constraint; the valuation cap and the 10-year limit on amortizing the business portion of the loan matter more. On smaller deals, its worked example shows how much rides on the salary assumed for a replacement manager:
- Seller's discretionary earnings: $100,000
- Annual debt service: $34,000
- Coverage with a $50,000 manager wage: 1.47x, above the floor
- Coverage with a $65,000 manager wage: 1.03x, below it
The salary a lender assumes for the new manager can decide whether a small restaurant deal qualifies. Sellers setting a price and buyers writing an offer should run the coverage math with a realistic wage before they agree on a number.
Key Takeaways
- SOP 50 10 8.1 as updated Sept. 25 governs applications SBA receives on or after Oct. 1, 2026.
- First-time buyers need 10% equity that can't be waived and 1.25x coverage on historical results.
- Acquisition debt can't exceed the business valuation, and seller earnouts are prohibited.
- Seller consulting is capped at 24 months; a seller note can be refinanced only after 36 months current and off standby.
Sources
MMCG Invest, “Restaurant Acquisition Feasibility Study under SBA SOP 50 10 8.1” (undated): https://www.mmcginvest.com/restaurant-acquisition-feasibility-study
U.S. Small Business Administration, SOP 50 10 8.1, Lender and Development Company Loan Programs, with Technical Policy Updates (effective Oct. 1, 2026): https://www.sba.gov/document/sop-50-10-lender-development-company-loan-programs
U.S. Small Business Administration, Information Notice 5000-882227, Issuance of Technical Updates to SOP 50 10 8.1 (Sept. 25, 2026): https://www.sba.gov/document/information-notice-5000-882227-issuance-technical-updates-sop-50-10-81
Images and Graphics
Chart: “Same restaurant, two salary assumptions,” built by SYR from MMCG Invest's worked example, with the 1.25x floor from SBA SOP 50 10 8.1, Appendix 15.